Struggling with Debt?
Free and impartial money advice is available from the Money Helper, an organisation set up by the Government for people in debt.
If you do not maintain the total contractual repayments to your creditors, this may negatively impact your credit rating.
If you qualify for a debt solution, you must read the small print to understand the Pros and Cons of each option available. Fees may apply depending on your qualifying debt solution.
Check your eligibility
To learn more about managing debt and receiving free, impartial debt advice, visit Money Helper or read about options for paying off your debt
If you are finding it difficult to meet your repayments, a range of debt solutions may be available. Whether any solution is suitable depends on your individual circumstances.
Formal debt solutions can reduce or stop most creditor contact, freeze interest and charges, and usually stop legal action, including enforcement. It may also be possible for qualifying debts to be written off, in full or in part.
It is essential that you fully understand the advantages, disadvantages and risks of any option before proceeding.
If you cannot pay your debts, you can apply to make yourself bankrupt online. Bankruptcy is a formal insolvency route and can have serious financial implications.
Creditors can apply to make you bankrupt, or you can apply yourself.
The three ways you can go bankrupt are: you apply for bankruptcy yourself, an application for bankruptcy from a creditor, or an IVA Supervisor if you fail to meet the terms of your Individual Voluntary Arrangement (IVA).
Key features:
Considerations:
You lose control of finances and assets; the official receiver or Trustee appointed on your case will decide what happens to your valuable assets and finances.
An IVA (Individual Voluntary Arrangement) is a legally binding agreement between you and your creditors to pay back your debts over a period of time.
If most creditors agree to your IVA proposal and it is accepted, you must agree to make regular payment contributions to an insolvency practitioner who will administer the IVA for both you and your creditors, and they will fairly divide your payment contributions between your creditors.
An IVA can give you more control of your assets than bankruptcy.
Key features:
Considerations:
A Debt Relief Order (DRO) is a way of dealing with your debts if you can’t afford to pay them. It means you don’t have to pay certain debts for a specified period (usually 12 months).
At the end of the DRO period, the debts included in it will be written off (‘discharged’), and you won’t have to pay them.
If you obtained any debts through fraud, you must restart paying them when the DRO has ended.
If your circumstances change to pay some or all of your debts, your DRO may be revoked so you can arrange to pay your creditors (the people or companies you owe money to).
To be eligible for a DRO, you must meet these criteria:
You won’t be eligible if you are involved in bankruptcy proceedings or any other formal insolvency procedure. However, if one of your creditors has asked a court to make you bankrupt, you may ask the creditor for permission to apply for a DRO instead.
Key features:
Considerations:
You must not break any of the restrictions
Your creditors can ask the Insolvency Service to investigate and get Debt Relief Restrictions Order (DRRO) against you if they believe:
A Debt Management Plan is an informal repayment agreement between you and your creditors to pay your debts.
Debt management plans are an alternative debt solution to formal, legally binding arrangements, such as an Individual Voluntary Arrangement (IVA) or Bankruptcy. They are available to residents in England, Wales, and Northern Ireland.
Debt management plans are typically used under the following circumstances:
Key Features:
Considerations:
An Administration Order is a repayment plan arranged by the County Court and is only available in England, Wales, and Northern Ireland.
An Administration Order legally binds your creditors and protects you from them.
The creditors included in the order cannot contact you for payment or add any more interest or charges to your debts once the administration order has been approved.
To apply for an Administration Order, you need to have:
Key features:
Considerations:
Breathing Space is a new debt option that gives you temporary protection from the creditors you owe money to if you are struggling with debts.
Key features:
There are two types of Breathing Space:
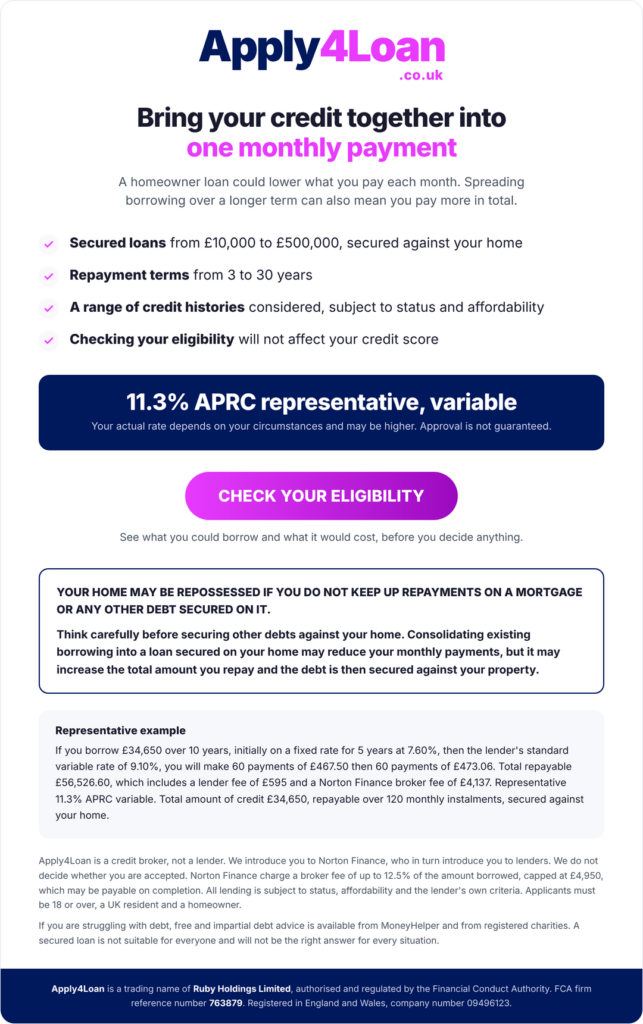
A homeowner loan (sometimes called a second-charge loan or secured loan) can be used for debt consolidation.
This means taking out one new loan, secured against your home, to repay multiple existing unsecured debts such as credit cards, personal loans, store cards or catalogues. You then make a single monthly repayment on the new loan instead of several separate payments.
Whether a homeowner loan is suitable depends on your individual circumstances, including your income, equity in your property, credit history and ability to afford the repayments. DebtSupportDirect.co.uk and Apply4Loan.co.uk are trading names of Ruby Holdings Limited. Ruby Holdings Limited is a credit broker, not a lender. We can introduce homeowners to credit brokers who may be able to arrange a secured loan – we do not make lending decisions and approval is not guaranteed.
Key features
Considerations
Important warnings
THINK CAREFULLY BEFORE SECURING OTHER DEBTS AGAINST YOUR HOME.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
IF YOU ARE THINKING OF CONSOLIDATING EXISTING BORROWING YOU SHOULD BE AWARE THAT YOU MAY BE EXTENDING THE TERMS OF THE DEBT AND INCREASING THE TOTAL AMOUNT YOU REPAY.
If you are struggling to meet repayments or are already in arrears, free debt advice is available from organisations such as MoneyHelper, StepChange, National Debtline or Citizens Advice. A formal debt solution may be more suitable than further borrowing in some cases. Always compare the total amount you will repay on any new loan with what you currently owe, and only proceed if you are confident you can afford the repayments for the full term.
The UK’s most detailed report and credit score with data from Experian, Equifax and TransUnion.
Start your 7-day free trial now, then it’s just £14.99 a month.
If you use the link on this page to obtain a credit report from CheckMyFile, Ruby Holdings Limited may receive a commission. This does not increase the cost of the service to you. CheckMyFile is the provider of the credit report service.

Search for a Personal Debt Adviser

A friendly & non-judgemental adviser will review and discuss your circumstances.

They will outline all the available options, allowing you to choose the best solution for you.


To learn more about managing debt and receiving free, impartial debt advice, visit Money Helper or read about options for paying off your debt